
- Darya Shaterloo, CEO and Founder
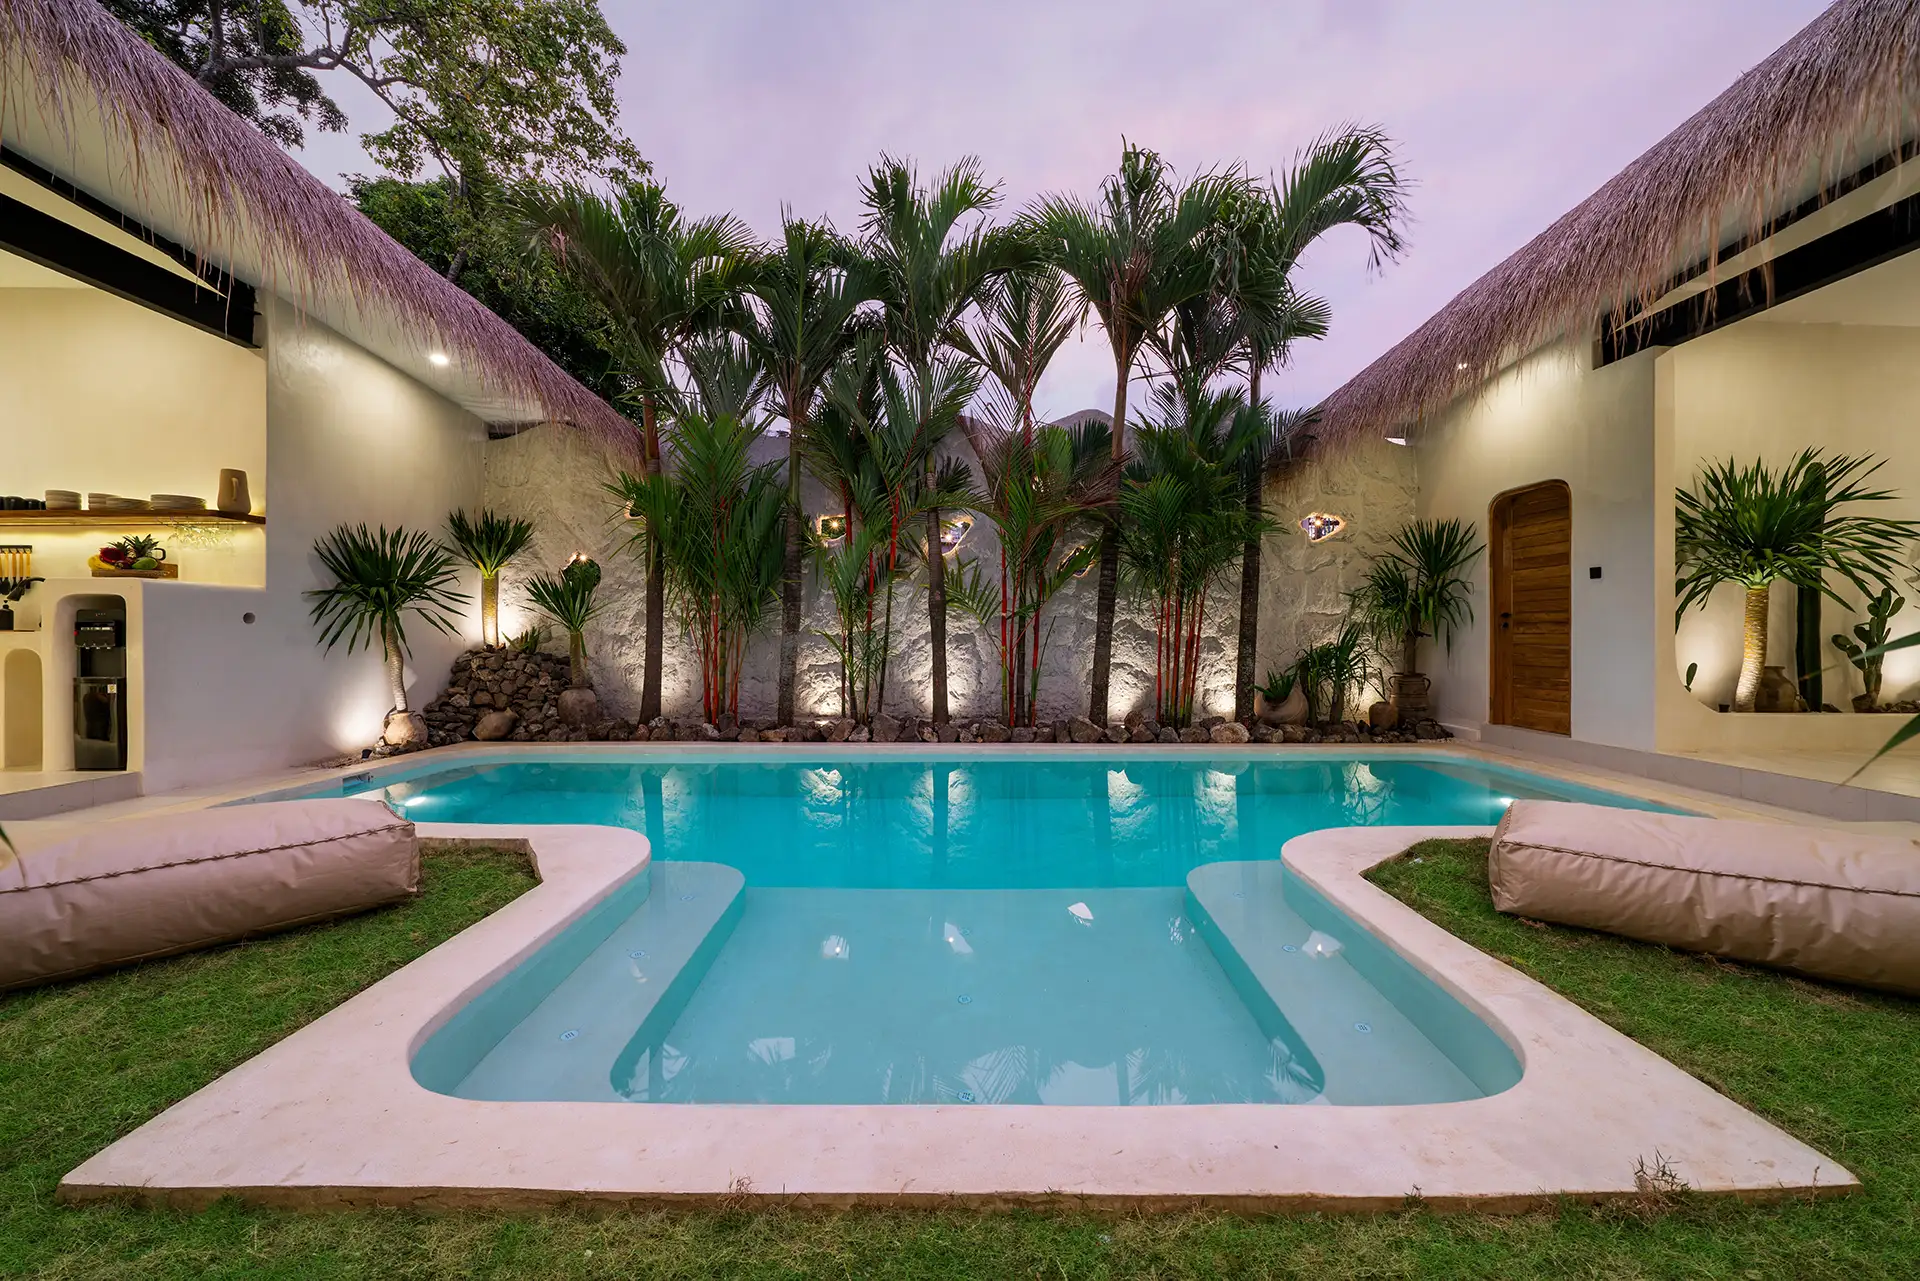
Hectocorn worked with a UK based client to secure development finance for the construction of a high specification luxury villa in [region], Spain. The site was secured and all the administrative and technical work needed for final building licence approval was complete. What the project needed now was the funding to build. The goal? Competitive, long term development finance from a lender comfortable with a UK based borrower building in Spain, without the client having to commit their own capital to the build.
Client Requirement
- Funding to complete construction of a high specification luxury villa
- Competitive pricing on a cross border transaction
- A lender comfortable with a UK based borrower and a Spanish asset
Sourcing competitive finance was crucial and required specialists. Most lenders are cautious about funding construction for non-resident borrowers, and the client wanted to keep full control of the project.
Outcome
We secured a long term development facility of up to €8.8M, covering 100% of the build costs.
- Development finance of up to €8.8M
- 60% to 70% loan to value
- 100% loan to cost (excluding VAT)
- Competitive pricing of 4% to 5%, including EURIBOR
- Long term facility with a 10 to 15 year term
Hectocorn Engagement
We managed the process from first approach through to completion.
- Reviewed the project, costs and licence position to present the strongest case to lenders
- Approached our network of Spanish and international lenders
- Compared offers on rate, leverage, term and drawdown structure
- Negotiated final terms and managed the process through to completion
- Worked alongside the client’s Spanish lawyers and project team
Our international lending relationships allowed us to secure terms the client would not have reached on their own.
Impact
- Build costs funded in full, keeping the client’s own capital free
- A 10 to 15 year term, so no pressure to refinance once the villa is finished
- Pricing of 4% to 5% including EURIBOR on a cross border development
This case shows Hectocorn’s ability to deliver customised financing solutions for UHNW clients, especially cross border development financing, where expertise and international lending relationships are essential.
Key Deal Highlights
Facility type: Development finance
Facility amount: €8,800,000
Loan-to-value: 60%
Loan-to-cost: 100% (excluding VAT)
Pricing: 4% to 5% including EURIBOR
Term: 10 to 15 years
Funding a development abroad? Our network covers lenders across Europe, the UK and beyond.
Discuss Your Development Finance Requirements Now!
Frequently Asked Questions
Yes. Spanish and international lenders will fund construction for non-resident borrowers. Expect lower leverage than a Spanish resident would get, and the lender will want the building licence in place and clear evidence of your income and wealth. You will also need an NIE, the Spanish tax identification number for foreigners.
Loan to cost compares the loan with the cost of the project. Loan to value compares it with the property’s value, often its value once complete. When the finished villa is worth much more than it costs to build, a lender can fund 100% of the costs while keeping loan to value at 60% to 70%.
Most lenders want the licence granted, or the administrative and technical work complete, before they release build funds. Having that in place, as this client did, makes a project far easier to finance.
Usually in stages as building progresses. Before each payment, a surveyor checks that the work has been done.
We’re an independent debt adviser, not a lender. We present your project to the right lenders, compare and negotiate terms, and work with your lawyers and project team through to completion.
IMPORTANT: The case studies featured on our website are based on genuine client enquiries and transactions handled by Hectocorn. All personal and identifying details have been anonymised to protect the privacy and confidentiality of those involved.
Case studies are published for illustrative and marketing purposes only, to provide context around the types of financing we arrange and the outcomes we achieve for our clients. In some instances, a case study may draw on elements from more than one transaction to better illustrate a particular scenario.
Please be aware that not every enquiry we receive results in a completed transaction. Where a case study is based on an enquiry rather than a concluded piece of business, this does not represent a completed deal. The publication of any case study on this website should not be interpreted as confirmation that the underlying transaction was finalised.